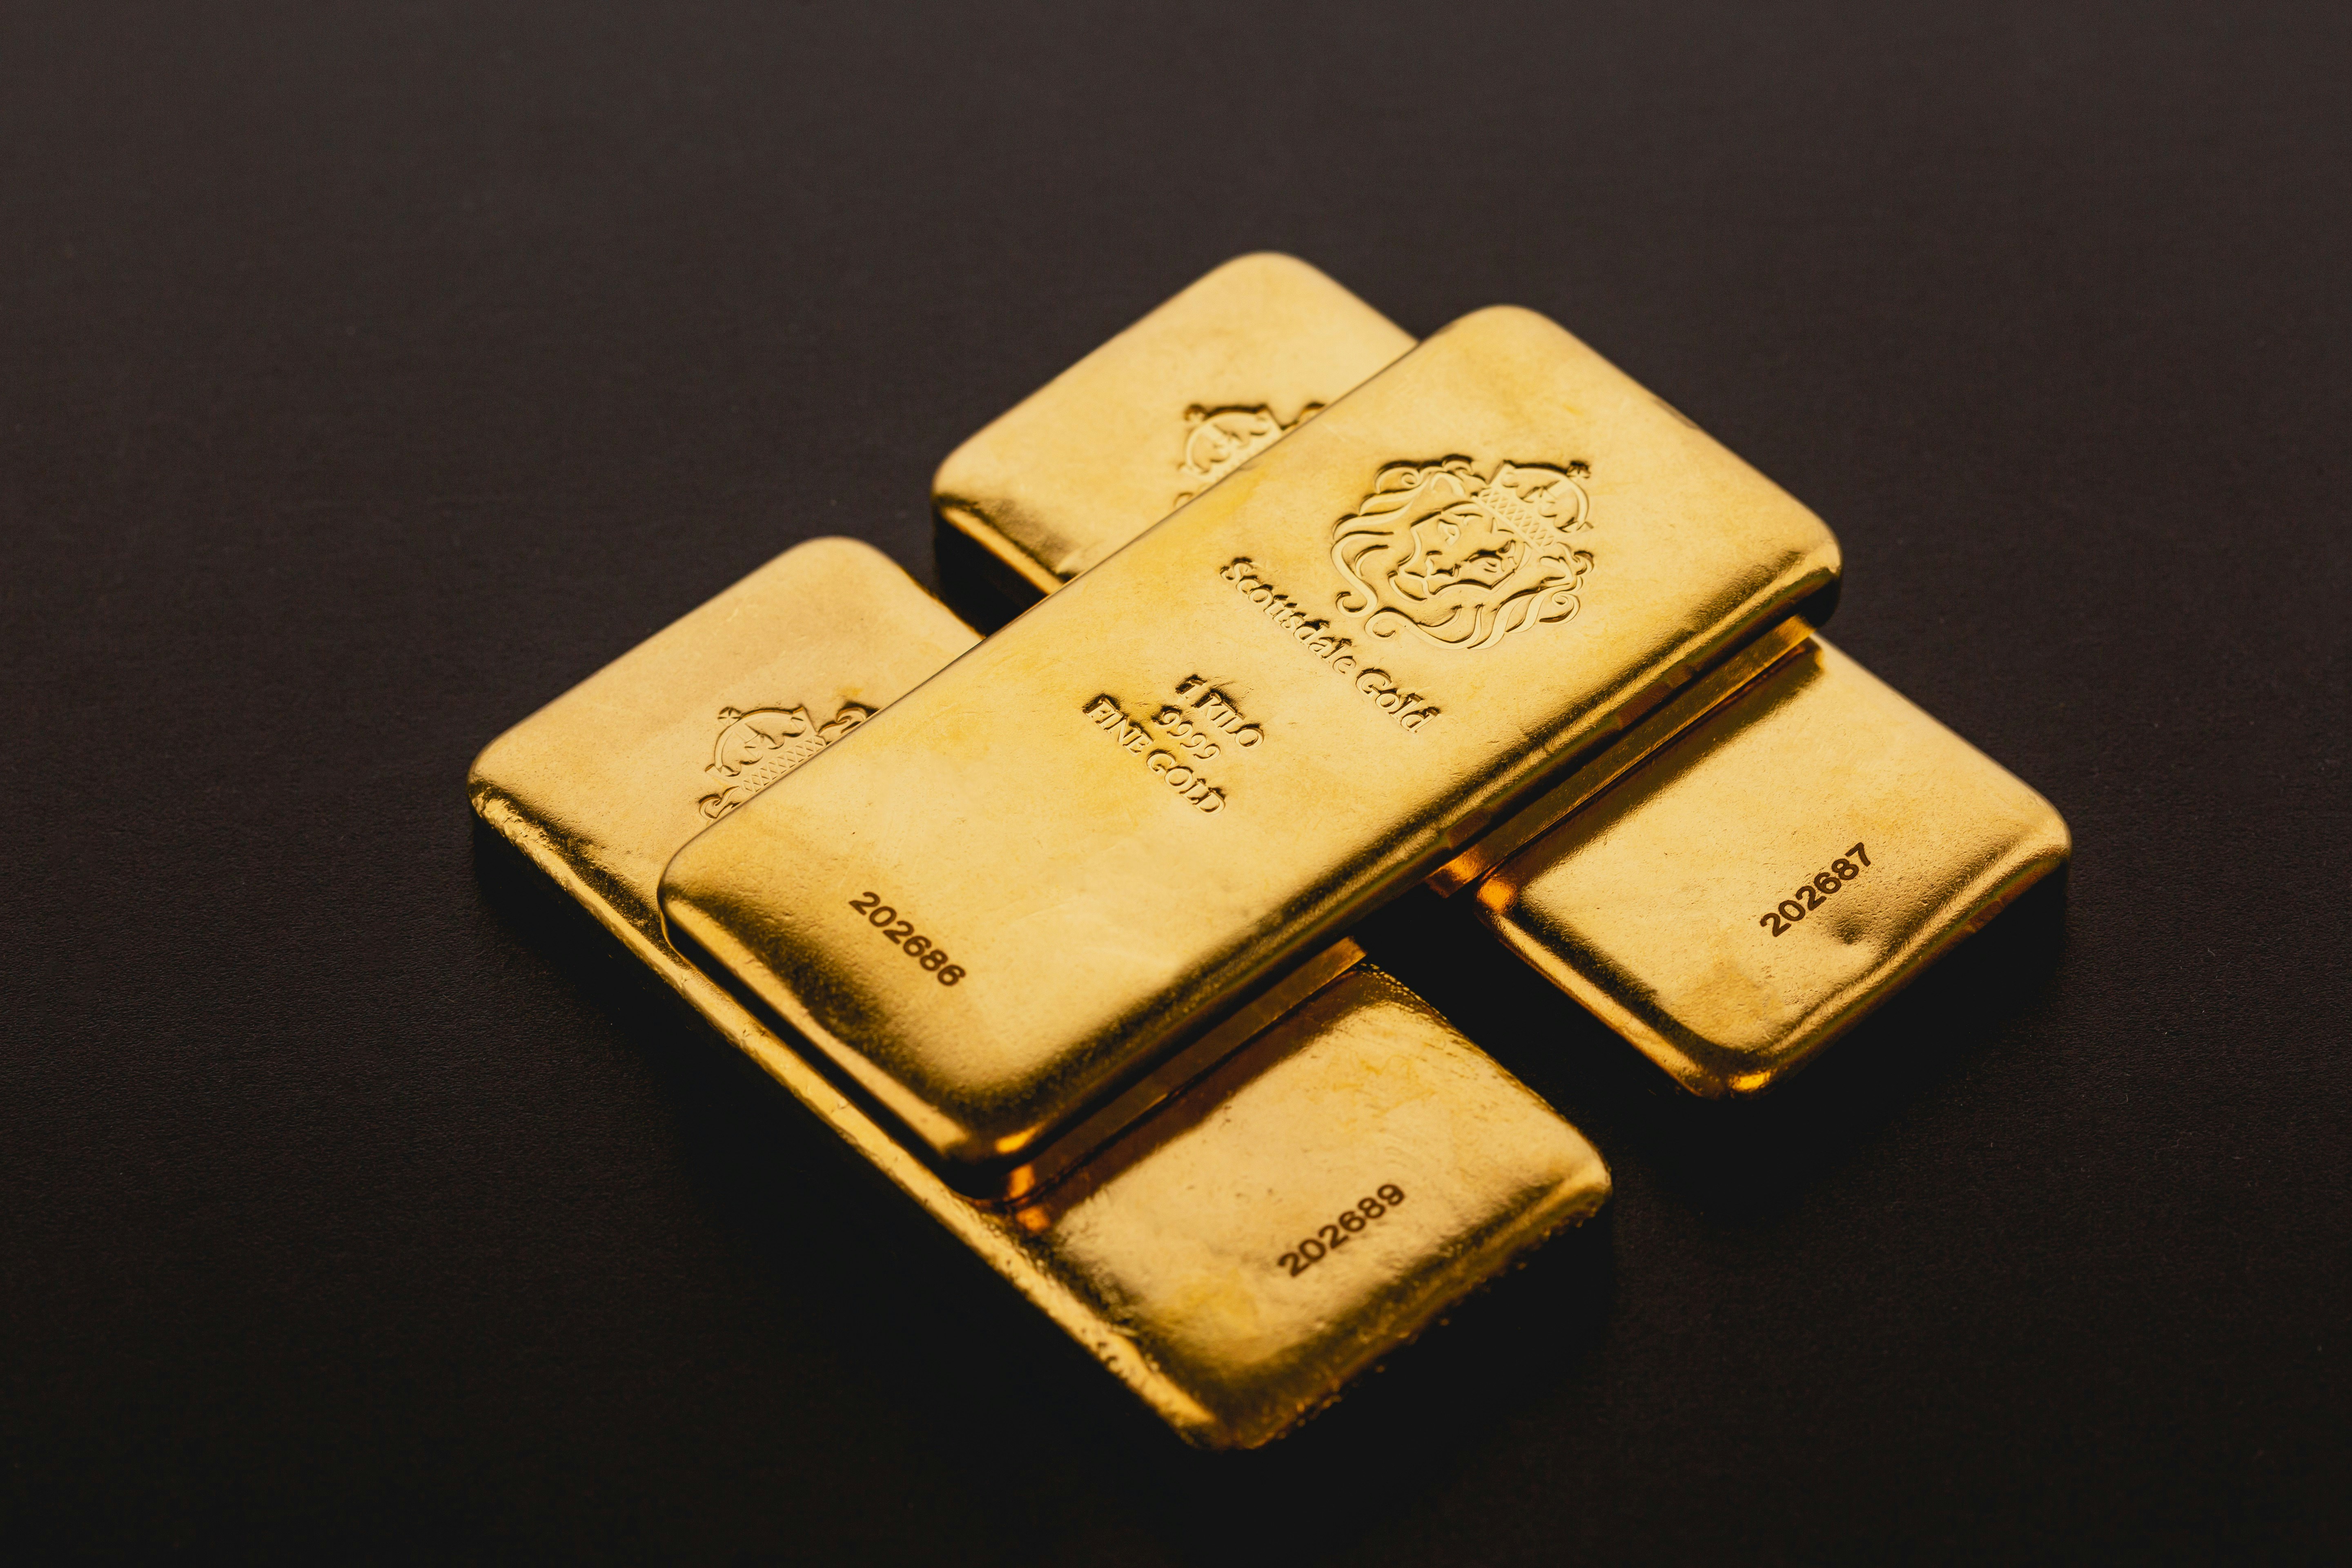
A 401(okay) rollover to bodily gold is a subject that sits on the intersection of retirement planning and valuable metals investing. For many savers, the motive is diversification, inflation safety, and a hedge against financial danger. But the path shouldn't be so simple as exchanging one asset for an additional. Buyers can't merely convert a traditional 401(k) into bodily gold and stash the bars at residence. As an alternative, the widespread route is to maneuver funds into a self-directed individual retirement account (SDIRA) that permits holding bodily treasured metals, after which acquire accepted types of gold inside that account. The metals are then saved in an IRS-authorised depository rather than taken into private possession. This report outlines how the method works, the regulatory framework, practical costs, risks, and alternate options to contemplate.
A 401(okay) rollover into bodily gold usually proceeds by way of a direct rollover into a self-directed IRA. The important thing distinction is between ownership and custody. You don't own bodily gold personally contained in the 401(ok) or SDIRA in your identify; quite, the plan property are held by a custodian or trustee, and the metals are saved in a separate, IRS-authorised depository. The IRS allows certain gold merchandise to be held in an IRA, supplied they meet purity and kind necessities and are saved with an accredited custodian. Widespread accepted options embody certain gold bars with excessive purity and authorities-minted coins, comparable to American Gold Eagle coins, that meet the IRS criteria. The exact record of eligible metals and coins varies by custodian, so potential buyers should consult their chosen SDIRA administrator for a definitive catalog of eligible assets.
Crucially, the rollover itself should be executed as a trustee-to-trustee switch or a direct rollover from the 401(k) plan to the SDIRA. A direct switch minimizes tax risk: if the rollover is completed correctly, the move is usually non-taxable. An oblique rollover, the place the funds are distributed to the account holder with a later redeposit into an IRA, introduces risk of tax withholdings and potential penalties if the funds should not redeposited throughout the allowed time-frame. For tax functions, rolling into a standard SDIRA maintains tax-deferred standing; converting to a Roth SDIRA would set off a tax bill within the yr of the rollover. It is essential to grasp these distinctions and coordinate with tax professionals to avoid unintended tax penalties.
Once funds are within the SDIRA, Thoughtlanes consumer summary the investor or the custodian can facilitate the acquisition of physical gold that meets the IRS requirements. The bodily metallic must be saved in an IRS-authorised depository; the owner cannot take possession of the metallic as a personal handover. Storage arrangements are a significant a part of the fee structure and threat profile. Most custodians companion with most popular depositories that present insured, secure storage with regular audits. The client retains economic exposure to the metal’s worth by way of the IRA, while the depository handles custody and security. The separation between possession, custody, and storage is a core characteristic of IRA-held bodily gold, designed to keep up compliance with tax regulation and custodial standards.
Costs are a practical consideration in a 401(ok) rollover to bodily gold. Typical fee components embody: (1) setup or account-opening charges for the SDIRA; (2) annual or quarterly custodial fees, often calculated as a percentage of assets under management (AUM) or as a flat price; (3) storage and insurance coverage charges charged by the depository; (4) treasured metals acquisition prices, including supplier premiums above the metal’s spot value; and (5) potential transport, integrity checks, and early-distribution charges if/when property are withdrawn. Rough ranges differ by provider and steel type but could embody, for example, setup fees from $zero to a few hundred dollars, annual custody and storage costs from roughly 0.4% to 1% of the account value plus fixed depository charges, and supplier premiums that replicate market situations. Buyers ought to get hold of a complete price schedule earlier than proceeding and evaluate multiple SDIRA custodians, emphasizing transparency about all ongoing prices and any potential exit or switch penalties.
From a regulatory and threat perspective, several factors deserve emphasis. First, the IRS controls that IRA-held treasured metals be stored in a method that ensures security, segregation, and accountability. The metal’s possession stays with the custodian and depository; the account proprietor does not bodily handle the metal except throughout a distribution, which is subject to taxes and potential penalties if completed before age 59½. Second, not all gold merchandise are eligible for IRA holding. Whereas government-minted coins just like the American Gold Eagle and certain bars are commonly accepted, specialised coins or collectibles could also be disallowed or treated in another way for tax purposes. It is crucial to verify eligibility with the SDIRA custodian earlier than buying. Third, gold worth volatility and liquidity concerns apply. While gold has historically served as a hedge towards inflation and a store of value throughout intervals of monetary stress, it is not a assured source of regular retirement income. The liquidity of a bodily-gold IRA is dependent upon factors corresponding to market demand, the flexibility to sell again to an accredited dealer, and the terms of the depository.
A key determination for traders is whether this rollover aligns with overall retirement targets and threat tolerance. The enchantment of holding physical gold inside a retirement account rests in diversification, potential inflation safety, and non-correlation with some monetary markets. The drawbacks include prices, regulatory complexity, and the absence of cash-circulation yields typical of equities or some bond funds. Moreover, because the asset kind is bodily metallic slightly than a claim on a company or on the monetary system, it could carry completely different liquidity dynamics and alternative prices, particularly if other investment alternatives carry out well over time. An goal analysis should quantify anticipated lengthy-time period returns, evaluate the cost of holding gold inside an SDIRA to various exposures similar to gold ETFs or bullion outside a retirement account, and consider how the holding matches with age, time horizon, and retirement revenue wants.
For readers who are exploring choices past a direct 401(okay) rollover into an SDIRA, there are alternate options to consider. A well known method is to allocate a portion of retirement property to a publicly traded gold ETF or mutual fund. ETFs corresponding to GLD or different bodily backed vehicles offer a manner to achieve exposure to gold price movements with out the prices and complexities of custodial storage within an IRA. However, these automobiles usually are not held inside an IRA themselves; fairly, they're investment funds held in brokerage accounts. They supply different tax implications and liquidity traits than physical gold held inside an SDIRA. An additional option is to diversify outside of retirement accounts, utilizing taxable accounts to buy physical gold or other precious metals. Each strategy has completely different tax impacts and danger profiles, and investors ought to evaluate these in mild of their retirement timelines and tax considerations.